8 Sep 2026
No-code deep link vs API integration in Embedded Insurance
By Tushar Kulkarni, Chief Product Officer | Updated 8 September 2026 |Estimated reading time: 9 mins
Summary
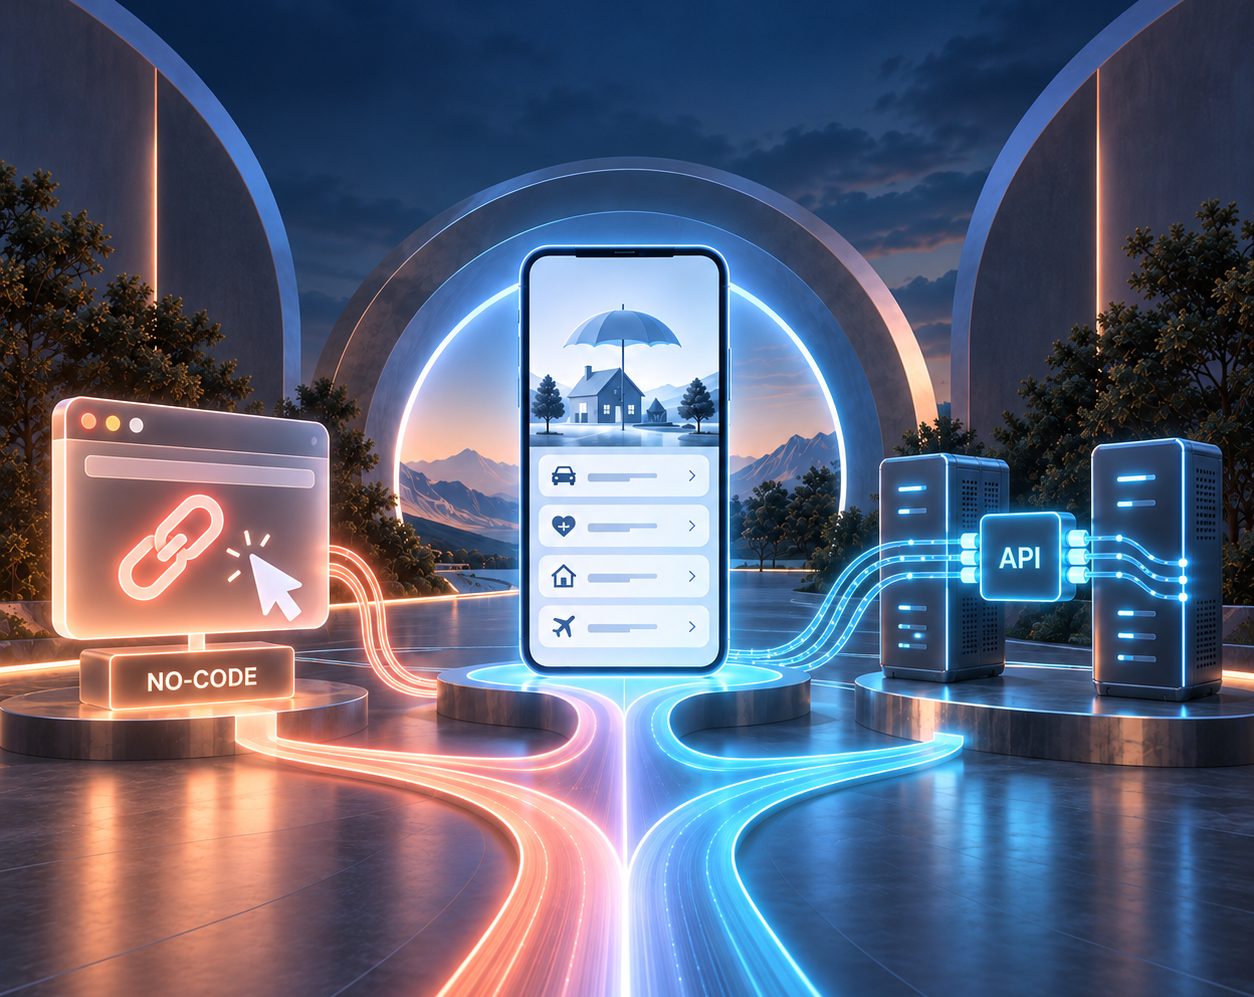
A deep-link purchase journey helps a business configure and launch embedded insurance using pre-built tools such as widgets, branded D2C sites or hosted forms. An API integration connects insurance with the business’s existing systems and can enable data to move in real time for quoting, policy issuance, servicing and claims. Many programs use both: deep-link purchase journey for faster configuration and APIs for real time data exchange.
The right approach depends on the customer journey, integration requirements, and launch priorities. Choose a deep-link route when a pre-configured customer journey fits the program and speed is the priority. Choose API integration when insurance needs to sit within an existing website, app or internal system and exchange data in real time. A hybrid approach is also common.
| Business need | Typical Approach | What it provides |
|---|---|---|
| Launch a standard, branded insurance journey quickly | Deep-link (no coding effort on partner’s side) | Pre-built tools for configuring products, rules and customer journeys |
| Embed insurance within an existing digital journey | API integration | Real-time data exchange between business and insurance systems |
| Configure products without coding and automate real-time processes | Hybrid | Purchase journey configuration supported by APIs behind the scenes |
Deep-link and APIs are therefore not strict alternatives. Deep-link describes how a product or journey is configured and deployed. APIs describe how systems exchange information and trigger actions.
Deep-link : configure and launch a pre-configured purchase journey
In this approach, the customer gets redirected to a separate purchase journey via the deep-link where the insurance application needs to be filled in to complete the insurance purchase.
Deep-link starts with technology that has already been built and arranged by the platform provider. Instead of designing every screen, rule and workflow from the beginning, authorized teams work within a pre-configured environment.
For product configuration, this would mean using a no-code product studio to define coverage, eligibility, pricing rules, customer questions, documents and claims workflows. For customer deployment, it would mean using a branded D2C site, embedded widget or hosted purchase form.
These options provide a clear starting point and can reduce the work needed to launch a proposition. The trade-off is between integration efforts vs the ease of purchase. Deep-link driven purchase journeys minimize tech effort on the partner’s side as bulk of the work is done by the embedded insurance platform provider, however the customer has to navigate through a separate insurance form to complete the purchase. This can introduce additional friction or a change in context, resulting in a relatively lower conversion rate.
A deep-link journey should not be construed as an absence of technology. APIs, databases, and automated workflows may still operate underneath the interface; they are simply hosted and orchestrated by the insurance platform provider.
API integration: connect insurance with partner’s existing systems
An application programming interface, or API, defines how two software systems can interact. It describes the requests that can be made, the information they contain and the responses another system can return.
In embedded insurance, APIs allow a business’s systems to exchange information with an insurer or insurance technology platform in real time. They can support eligibility checks, quotations, policy issuance, documents, servicing and claims updates in real time or asynchronously, depending on how the integration is designed.
Consider a customer purchasing a flight. The booking platform already knows the destination, travel dates and value of the booking. An API-enabled flow can send the relevant authorized information to the insurance platform, apply the configured rules and return an offer. If the customer accepts, the policy can be issued and its details returned to the booking account, without the customer requiring to leave the flight ticket booking journey.
The same principle applies to banking, mobility, e-commerce and potentially any other business where insurance can be embedded into a non-insurance offering. Insurance responds to an event that is already taking place instead of asking the customer to begin a separate process. The amount of implementation work depends on how the APIs are designed and orchestrated.
Why more APIs do not necessarily mean a better platform
API quantity is easy to promote because it produces an impressive number. It is also a poor measure of how easy a platform will be to integrate and operate.
If every insurer, product or process has a separate interface, a business may need to repeat the same mapping, authentication, testing and error handling work. Each connection may also use different terminology, data structures and release cycles. A large API catalogue can therefore create more manual configuration rather than meaningful reusability.
A better assessment focuses on outcomes. Do the APIs cover the insurance lifecycle from quotation and issuance to servicing and claims? Do they use consistent data structures? Can one connection support multiple products or partners? Are the workflows already linked, clearly documented and versioned? The aim is not the highest API count. It is a coherent set of capabilities that can operate reliably and change without unnecessary complexity.
The middle ground: pre-orchestrated APIs
Pre-orchestrated APIs sit between fixed technology workflows and a varying collection of products, interfaces and data that a partner assembles for various propositions. Common steps such as eligibility, quotation, issuance, documents, servicing and claims are already connected. The partner business team can then configure which capabilities it needs, what should trigger them and where the information should go.
This is called an intelligent API approach. In this context, “intelligent” does not necessarily mean that the API uses artificial intelligence. It means that the provider has already arranged reusable insurance processes, consistent data structures and status changes so the connection can adapt across products and partners.
Good documentation, versioning and error handling are part of this approach. They allow the business to configure a useful data flow without requiring a large specialist team to engineer every insurance interaction from scratch.
How discovermarket combines deep-link purchase journeys and APIs
discovermarket brings these layers together on one platform. Its Product Studio enables insurance solutions to be configured without coding, while its Product Library provides ready-to-use product structures. Depending on the program, insurance can then be distributed through an API, SDK, widget or branded D2C site. discovermarket technology
For a business that wants a ready-made route, our widget or branded D2C site provides a pre-configured customer journey. For a business that needs insurance to sit natively within its own platform, discovermarket’s APIs provide access to pre-orchestrated capabilities. The partner can configure how relevant data and processes fit into its customer and operational flows, reducing the need to build and manage each underlying insurance interaction separately.
The discovermarket Developer Portal documents consistent request and response formats, standard HTTP methods, versioning and secure authentication options. These foundations do not remove the need to define requirements, map authorized data and test the journey. They reduce the insurance infrastructure each partner must design and connect independently.
How should a business choose?
The decision should begin with the customer journey and operating model, not with a preferred technology label.
| Consideration | Deep-link journey | API integration | Hybrid approach |
|---|---|---|---|
| Customer experience | The customer moves to a separate hosted insurance flow | Insurance can remain within the partner’s existing journey | The experience may combine native and hosted steps |
| Initial Technical Effort | Usually lower for the distribution partner | Usually higher because systems and data must be connected | Can be phased around the processes that need deeper integration |
| Data Exchange | No system to system data exchange. Customer enters data directly on the hosted journey | Can support real-time or asynchronous exchange across connected systems | APIs exchange data for selected processes |
| Journey control | Configuration remains within the options supported by the hosted flow | The partner has more control over the experience in its own interface | Control varies by stage of the journey |
| Ongoing ownership | The embedded insurance platform manages the hosted journey; the partner still manages placement, links, tracking, and testing | The partner owns the integration, monitoring, testing, and change management | Responsibilities are shared according to the chosen design |
| Typical fit | A faster launch, pilot, or standardized purchase flow | A native journey or program requiring deeper system connectivity | A program that needs native integration for some steps but not the entire lifecycle |
A pre-configured journey may be enough when the program follows a standard purchase flow, speed is the main priority and a branded D2C site, widget or hosted form provides sufficient control. It can also help test whether customers understand and value the proposition before more systems are connected.
An API-enabled flow becomes more important when insurance must sit natively within an existing app, information needs to move in real time, or several systems require policy data. It can also provide a stronger foundation when the program expects to expand across products, partners or markets.
The choice does not need to apply to the whole program. A business might configure products through a no-code studio, use APIs for quotation and issuance, and rely on a hosted portal for documents and claims. Product configuration, customer presentation and data exchange are separate decisions.
Technology is also only one part of the program. The participants must still agree on the product, insurer approval, regulatory responsibilities, payments, communications, policy servicing and claims. Both approaches require appropriate security, privacy and access controls.
Frequently asked questions
Does API integration always require a development team?
Not necessarily a large or specialist team. The effort depends on the API design, documentation, orchestration and the business systems. Pre-orchestrated APIs reduce the need to assemble every insurance process or connect separately to every product and insurer. A live integration still requires clear ownership, secure configuration and testing.
Does deep-link purchase journey mean that no APIs are involved?
No. Deep-link purchase journeys often use APIs behind the scenes. These can be hosted by the insurance platform provider, thus minimising integration efforts on partner’s side.
Are more APIs always better?
No. A high API count can indicate fragmentation and repeated configuration. API quality is better assessed through lifecycle coverage, consistency, documentation, reusability, security and the ability to configure useful data flows.
Can a business begin with deep-link and move to APIs later?
Yes, if the platform supports both. A business can start with a pre-configured purchase journey and connect additional systems or configure more specialized data flows as the program develops.
The real integration question
The right choice is rarely all or nothing. A deep-link purchase journey can provide a ready-made route with less partner-side integration, while APIs can support a more native experience and deeper data exchange. The two approaches can also work together across different stages of the same program.
The more useful question is: which parts can follow a proven, preset journey, and where does information need to flow according to the business’s own customer and operating model?
About discovermarket
discovermarket works with insurers and distribution partners to build and operate digital insurance programs. Our technology supports product configuration, quotation, policy issuance, servicing, claims and reporting, while our teams work with partners on the commercial and operational setup required to launch and run the proposition.